Business Correspondent
Bard Santner Inc, a Harare-based financial services group, has secured a deposit-taking microfinance bank licence as it moves to establish a diaspora banking and investment platform designed to serve Zimbabweans and other Africans living and working across the continent and worldwide.
The deposit-taking microfinance bank is a foundation for the longer-term banking ambitions of the Bard Santner Group, which has offices in Harare, Johannesburg, South Africa, and New York, United States, as it develops a diaspora-focused institution, the first of its kind in Zimbabwe and the region.
South Africa boasts the most developed financial technology ecosystem in Africa, including digital banking and neobanks, reaping 40% of the continent’s entire fintech market revenue.
Driven by high smartphone penetration and progressive regulatory support, digital fintechs are transforming financial access for both consumers and underserved small businesses.
Bard Santner Bank’s diaspora-focused model is unique, but it will pick lessons from other already thriving banking fintechs like GoTyme Bank and Bank Zero in South Africa.
The Reserve Bank of Zimbabwe has announced the licence and regulatory approval of Bard Santner Microfinance Bank, a deposit-taking microfinance bank.
In a public notice, the RBZ said:
“Notice is hereby given, in terms of the Microfinance Act (Chapter 24:30), as read with section 5 of the Microfinance (General) Regulations, 2025, (SI 85 of 2025), of the registration of Bard Santner Microfinance Bank Limited as a deposit-taking microfinance institution with effect from 1 October 2026.”
The licence lists 15 authorised activities of the bank:
1. Receiving savings deposits;
2. Extending credit, including:
a) consumer and mortgage credit;
b) factoring, with or without recourse;
c) the financing of commercial transactions;
d) the recovery, by foreclosure or other means, of amounts so extended;
e) forfaiting, that is to say, the medium-term discounting without recourse of bills, notes and other documents evidencing an exporter’s claims on the person to whom the exports are sent.
3. Bank Guarantees;
Export and Import facilitation subject to Exchange Control Act [Chapter 22:05];
5. Structured Finance;
6. Buying and selling instruments, whether for the account of the microfinance bank concerned or for the account of its customers, including the underwriting of money market instruments, bills of exchange and certificates of deposit;
7. Providing money transmission services;
8. Subject to the Exchange Control Act [Chapter22:05], buying and selling foreign currencies;
9. Issuing and administering means of payment, including credit cards, travellers’ cheques and bankers’ drafts;
10. Money broking;
11. The safekeeping and administration of valuables, including securities;
12. Providing services as a portfolio manager or adviser or as a financial agent or consultant;
13. Financial leasing;
14. Entering into or taking cession of hire-purchase contracts in accordance with the Hire Purchase Act [Chapter 14:04]; and
15. Providing credit reference services.
The bank will provide all these services, with emphasis on diaspora remittances, an area where Bard Santner was already involved in through its subsidiary, TX Money
Transfer, one of Zimbabwe’s most reliable and efficient remittance services.
Bard Santner Bank will operate as a cross-border financial connector, engineered around real-time payments and a banking architecture purpose-built for diaspora flows and SME trade.
The opportunity is huge.
Zimbabwe’s diaspora remittances reached US$2.45 billion in 2025, a 14% increase on the prior year and roughly 16.1% of total foreign currency earnings.
Formal remittances reached US$1.62 billion in the first seven months of 2026, up 24% on the same period in 2025, according to the RBZ.
Remittances play a huge role in the African financial and development architecture.
African diaspora remittances reached an estimated US$124.2 billion in 2025, surpassing foreign direct investment and official development assistance across the continent.
Africa’s collective GDP is approximately US$3.4 trillion, with a total population of roughly 1.5 billion people.
Most of its trade happens within the African Continental Free Trade Area, a massive free trade agreement that unites 54 member countries of the African Union to form the world’s largest free trade zone by number of countries.
Yet for all the volume, remittances have rarely been treated as capital. They have been treated as cash for consumption rather than inflows for investment and development.
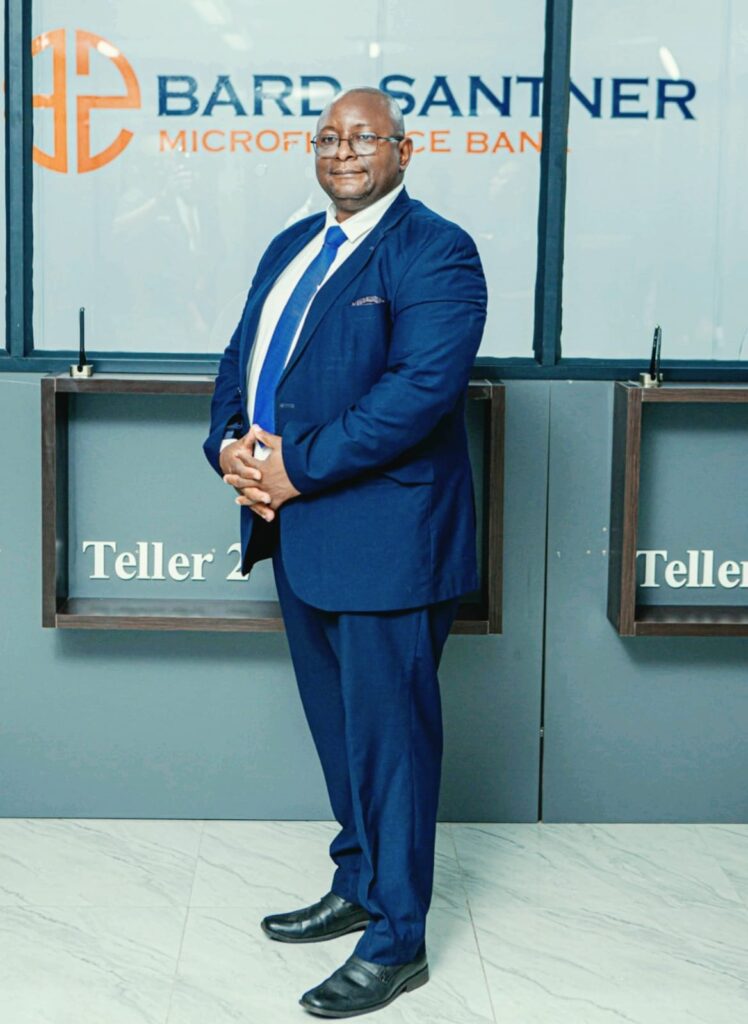
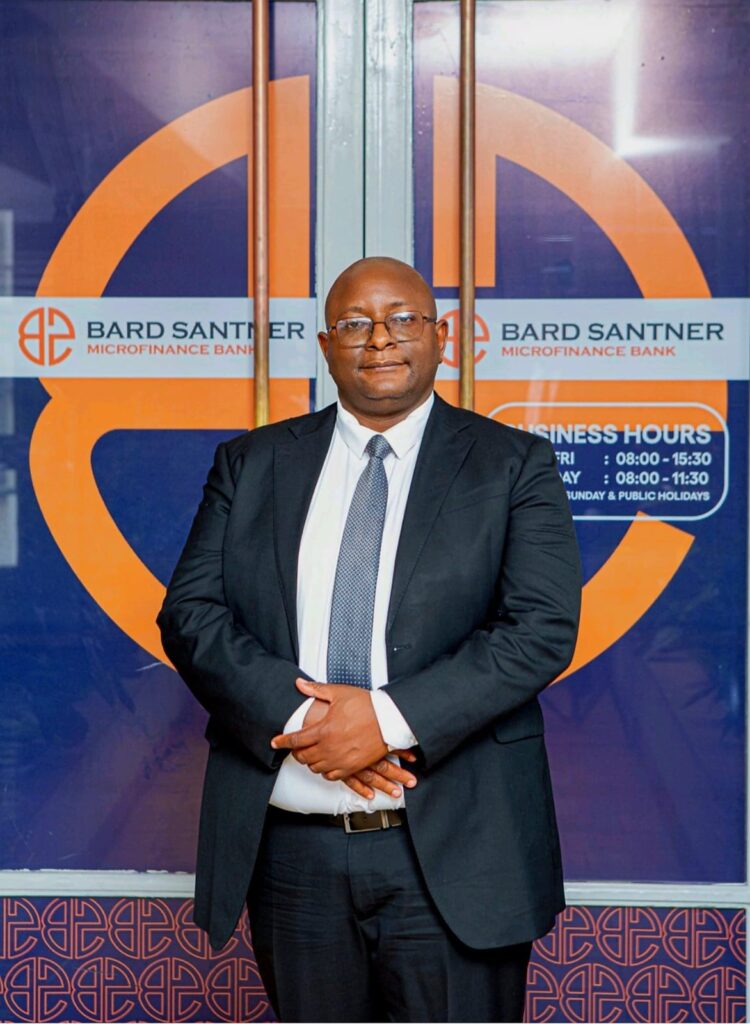
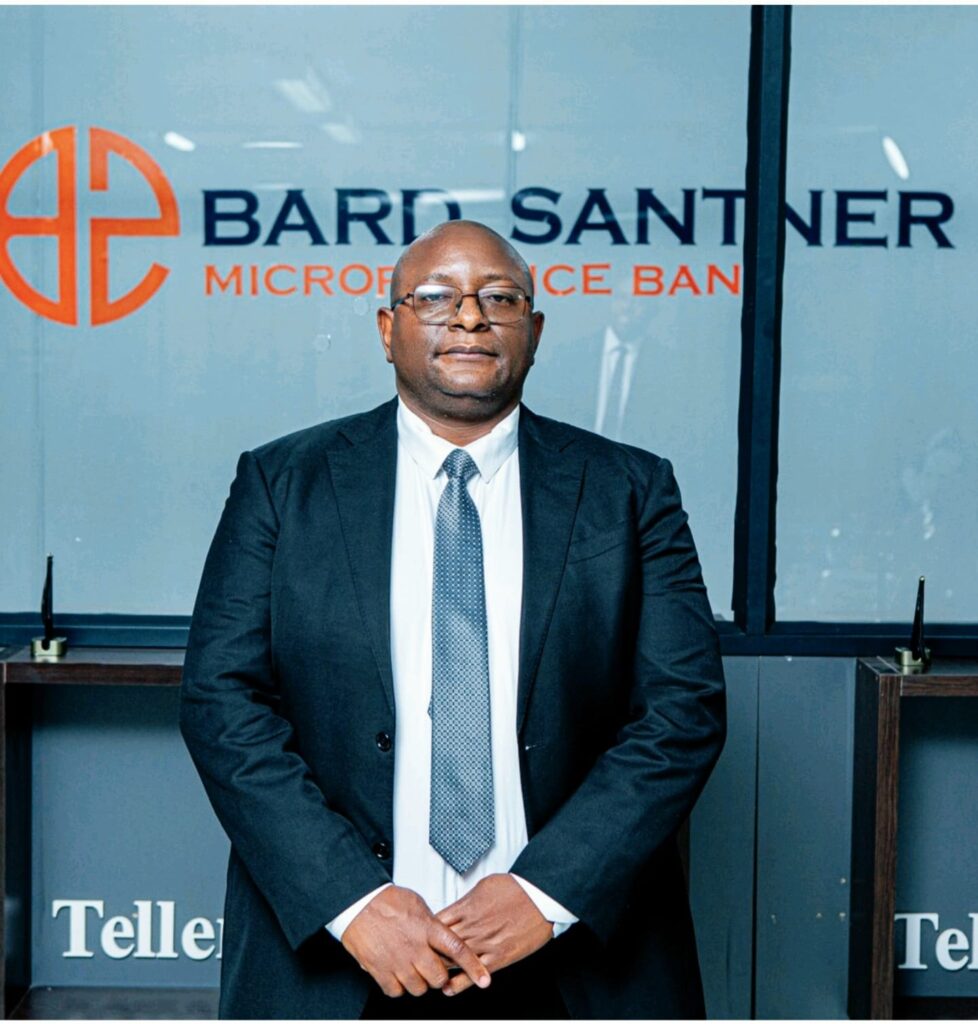
Bard Santner Bank Managing Director Ngonidzashe Chikowore says that must change.
“This is not the launch of just another start-up bank,” Chikowore.
“Zimbabwe and Africa do not need another bank for the sake of a bank.
What our people need — at home and abroad — is an institution, no matter how small to start with, that meets them where they live, earn, transact and aspire.
We are a start-up institution, but we know that is the digital era it is not always about scale.
Yes, size matters but so does agility.
In the digital era, agile and technology-driven banks frequently outperform traditional financial giants by prioritising customer experience over asset size.
While large legacy banking institutions benefit from massive balance sheets and economies of scale, smaller digital-first banks and fintechs use speed, cutting-edge technology, and hyper-personalised service to win over modern consumers.
The shift from ‘size-first’ to ‘service-first’ banking highlights how technology is redefining competitive advantages in banking and finance.”
Chikowore says while Bard Santner Bank has ambitions to grow and secure a merchant or commercial banking licence, their focus is not primarily on scale, but agility and utility.
“Winning institutions view banking not as a series of physical locations, but as an invisible, embedded utility.
They design services around the user’s life events rather than the bbank’s own internal products, personalised services.
Modern consumers expect financial interactions to feel like ordering a ride-share, a pizza or streaming a movie.
This means 24/7 availability, instant loan or transaction approvals, where applicable, and predictive financial insights driven by AI.
Digital-first banks operate with a fraction of the cost-to-income ratio seen in traditional banks. By replacing manual paperwork with automated APIs, they pass savings back to customers via higher interest yields and lower fees.”
Chikowore says Bard Santner Bank will offer a digital and cross-border service operating within the established Zimbabwean jurisdiction framework and regulations, yet global by scope and utility.
“A nurse in Manchester, UK, or doctor in Melbourne, Australia, a restaurant worker in Johannesburg, South Africa, should be able to send money home or fund a business in Harare or Bulawayo as easily as he or she pays an electricity bill electronically, order an Uber or pizza digitally.
A businessman in Harare, Johannesburg, Nairobi or Cairo should be able to invest in Lagos without losing a week to settlement delays. That is the concept and standard we are bringing.”
Bard Santner Bank says this is not a traditional bank acquiring a digital layer. Instead, it is a digital institution acquiring a deposit-taking microfinance bank licence to provide Zimbabweans, Africans and global citizens with first-class financial tools tailored to their cross-border lifestyles.
For too long, African banking has been shaped by infrastructure designed for a slower world — branch-heavy, paper-bound, domestically confined, and structurally incapable of serving a generation that earns in one currency, lives in another country, and builds wealth across three.
Analysts have welcomed Bard Santner Bank the regulated financial ecosystem, saying its specialised focus on the diaspora will deepen financial markets, increase foreign currency inflows, and provide clients abroad with “a safe, compliant, and innovative platform”.
Products will be designed for mobile-first customers and structured around the realities of cross-border life — multi-currency accounts, instant remittance-to-investment conversion, diaspora-linked savings instruments, and SME trade finance built for African corridors.
As a deposit-taking microfinance bank, Bard Santner Bank falls within the regulated deposit-taking framework, subject to capital adequacy standards, governance requirements and ongoing supervisory oversight.
The licence allows the bank to offer a full range of banking products, from deposits and savings to lending and payments.
BSMB has signalled that its rollout will be phased, disciplined and grounded in international best practice, with full banking operations expected to commence soon.
“The licence is not merely a vote of confidence in Bard Santner, but also a responsibility,” said Chikowore. “Durable institutions are not built on speed alone. They are built on capital, corporate governance and trust.”
Bard Santner Group chief executive Senziwani Sikhosana said the bank aims to become the next-generation financial institution built to empower the global diaspora.
“Securing this deposit-taking microfinance bank licence is a transformative moment for millions of Zimbabweans and other global citizens who call more than one country home.
“We will not just be moving money; we are bridging people and economies. This licence allows us to build a trusted foundation where the diaspora can save, invest, and grow their wealth securely, directly contributing to individual, organisational and national economic development of their home countries in a structured and sustainable way.”