By Kudzai Jakachira
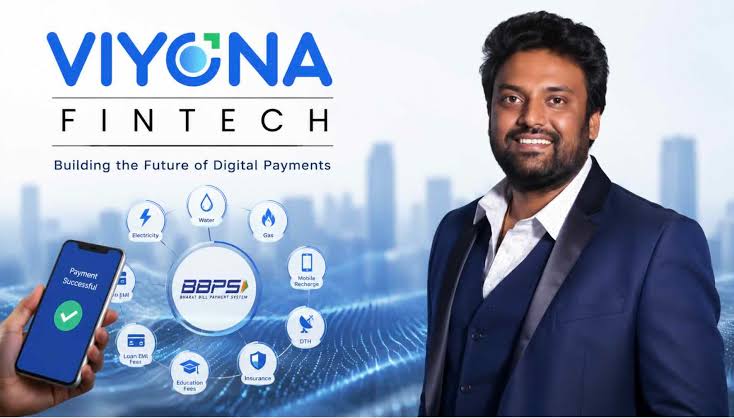
Indian financial technology company Viyona Fintech is targeting Zimbabwe as its entry point into the African market, with plans to introduce a smartphone-based contactless payment solution aimed at reducing transaction costs for small businesses.
The company plans to roll out its Viyona Tap & Pay platform in Zimbabwe as part of a broader expansion into sub-Saharan Africa, with discussions underway with the Government of Zimbabwe to facilitate the proposed launch.
The platform uses Near Field Communication (NFC) technology to turn compatible Android smartphones into contactless payment terminals, potentially allowing merchants to accept digital payments without purchasing dedicated point-of-sale (POS) machines.
According to a report published by technology news platform CXOToday on Monday, Viyona is identifying local acquiring banks, payment service providers and merchant networks as potential partners for integrating the technology into Zimbabwe’s payments ecosystem.
Viyona founder and chief executive Ravindranath Yarlagadda said the company’s focus was on providing scalable digital infrastructure that reduces capital expenditure for merchants.
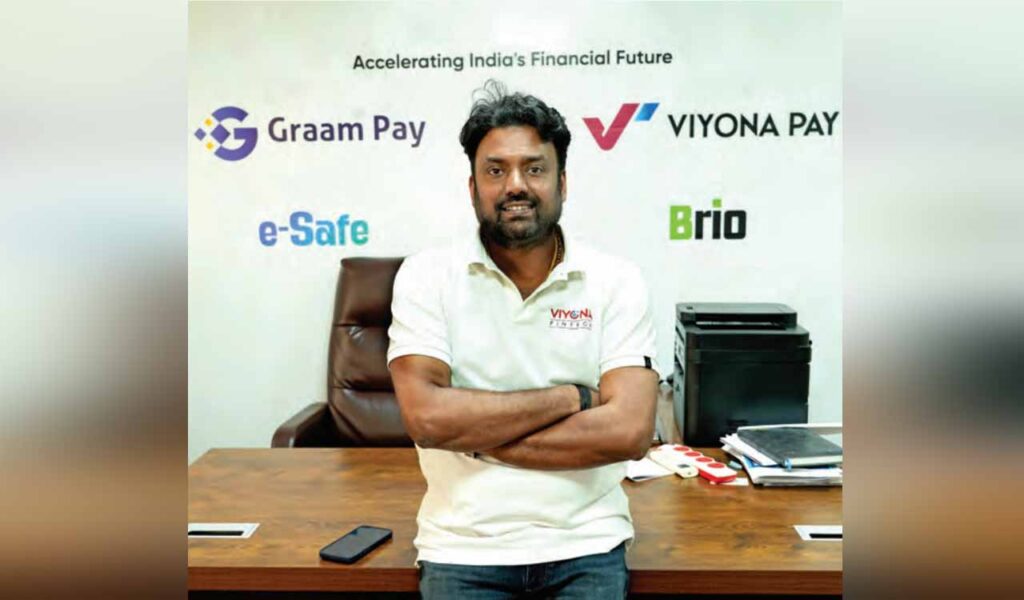
He said Zimbabwe’s growing digital payments market made it a suitable entry point for the company’s planned expansion into the region.
The company cited monthly electronic transactions exceeding ZiG200 billion in Zimbabwe as evidence of the market’s potential.
The proposed rollout is expected to follow the necessary payment network certifications and regulatory approvals before full commercial deployment.
The expansion comes as Zimbabwe explores the adoption of India’s Unified Payments Interface (UPI) technology to develop a domestic real-time payments system. The Reserve Bank of Zimbabwe is in negotiations with NPCI International Payments Ltd, the international arm of India’s National Payments Corporation, over the proposed arrangement. The proposed UPI-based infrastructure could connect banks, fintech companies and mobile money operators, allowing users to transfer funds instantly across participating platforms.
Viyona’s planned entry into Zimbabwe could complement such infrastructure by providing merchants with technology to receive digital payments. However, the company’s proposed deployment remains subject to regulatory clearances, payment network certification and the establishment of local partnerships.
Viyona is positioning the technology as a way to lower the cost of accepting electronic payments, particularly for micro, small and medium-sized enterprises that may find conventional POS equipment expensive.
Under the SoftPOS model, merchants use compatible smartphones to accept contactless payments, potentially reducing the need to purchase and maintain separate payment terminals. Actual availability and the payment methods supported in Zimbabwe would depend on the final implementation and participating financial institutions.
The company is seeking to enter a wider African market that is experiencing rapid growth in instant digital payments.
According to the AfricaNenda Foundation’s State of Inclusive Instant Payment Systems in Africa 2025 report, African instant payment systems processed nearly US$2 trillion across 64 billion transactions in 2024. The report identified 36 live systems across 31 countries as of June 2025.
The figures highlight the growing importance of digital payment infrastructure in facilitating commerce, improving financial inclusion and connecting consumers and businesses to formal financial services.